
Pubs, hotels and taverns
Front bar, bistro, beer garden and often rooms upstairs. We'll ask about each part of the building and how late you trade.
We broker insurance for pubs and other licensed venues. We get quotes for your cover from insurers, then help you compare them.
In 2023, the National Insurance Brokers Association (NIBA) named Frans du Plessis its WA Broker of the Year.
We try to reply within 24 hours. We look for at least 2 quotes, and up to 12.
What a venue can insure
For a pub or bar, the usual starting point is public liability, plus cover for the building, the fit-out and the stock. What you add after that depends on how the venue trades, such as a large cool room, high cash takings, online bookings or employed staff. We arrange cover for licensed venues all over Australia, including each of the covers below.
Covers you if a customer or passer-by is hurt, or their belongings are damaged, and they hold your venue responsible. For licensed venues it can include risks from serving alcohol.
Can pay the claim when goods from your venue, sold or given away, hurt a person or damage what they own.
Covers the building if you own it, plus the bar fit-out, furniture and stock, so they can be fixed or replaced after a fire or other damage your policy covers.
If a fire or other damage your policy covers shuts the venue, it can cover lost income and some ongoing costs. Your broker checks which costs each quote includes, and for how long.
Pays to repair cool rooms, kitchen gear, cellar equipment and other machines when they suddenly break down.
Pays for food and other chilled stock that spoils when a fridge or cool room fails. Insurers call this stock deterioration.
Covers cash and stock stolen in a break-in, up to the limits on your policy, and replacing broken shopfront glass and display cabinets.
Cover if your till system or online bookings are hacked, or customer data is stolen. Ask your broker what each policy would pay for.
Covers your staff if their job injures them or makes them ill. The law says nearly all employers need it, and the rules depend on your state or territory.
Covers directors and managers if someone accuses them of mismanaging the business. Some policies also cover claims from staff, such as unfair dismissal.
Need help choosing? Tell us how the venue operates and your broker will go through the list with you.
Get a quoteVenues we look after
A pub, a nightclub and a cellar door run very differently, so before we go to insurers we ask different questions about each one.
Front bar, bistro, beer garden and often rooms upstairs. We'll ask about each part of the building and how late you trade.
Bars often stay open late and go through a lot of glassware. Expect questions about your trading hours, security and fit-out.
Nightclubs trade late with large crowds and security staff on the door. We'll ask how many people you hold and who runs your security.
A board or committee runs the club for its members. Along with the building, we'll ask who sits on the board.
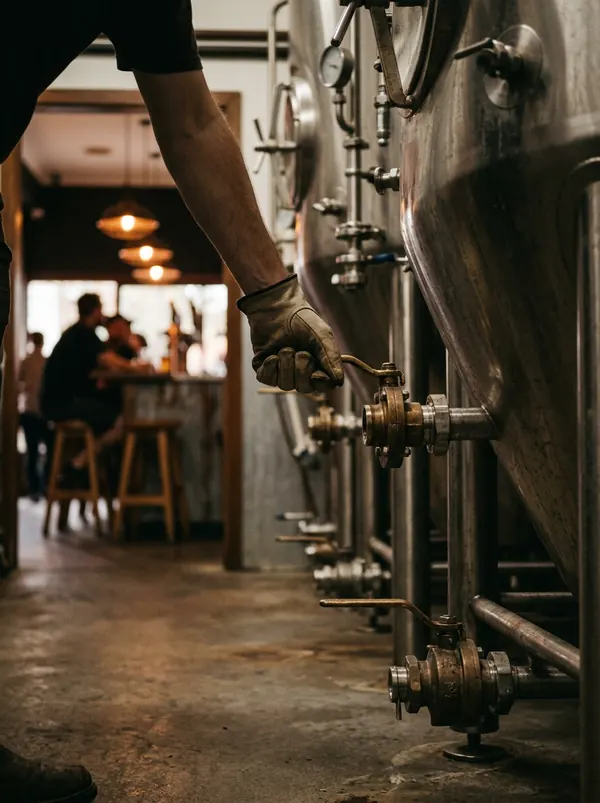
You make the beer or spirits on site as well as pour them. We'll need details of your brewing or distilling gear, your stock and your tasting room.
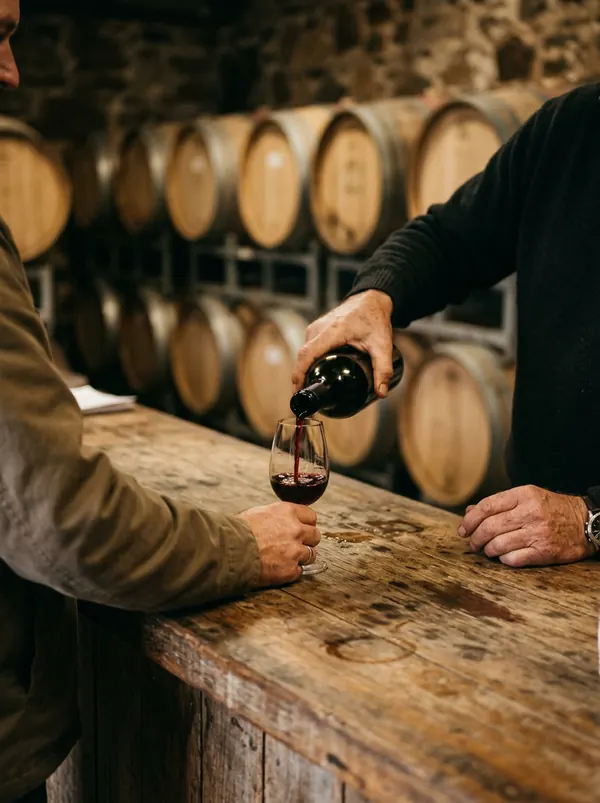
Visitors come to taste and buy wine on site. We'll ask about tastings, events and where your stock is kept.
Is your venue a mix, say a pub with a brewery out the back? Pick whichever is closest on the form, and we'll ask about the rest when we reply.
Get a quote
From form to policy
Tell us about the venue and a broker will deal with the insurers for you. We stay in contact after the policy starts, at renewal and if you need to claim.
The quote form at the top has six short steps and takes about two minutes. If a phone call suits you better, ring 1800 556 777, Monday to Friday, 8:30am to 5pm Perth time (AWST).
Our aim is to reply within 24 hours. Your broker then asks you about what the form doesn't cover, such as your trading hours and the building, so the insurers know what they're quoting on.
Your broker passes the venue's details to insurers and asks for prices. We have more than 160 to pick from, and the goal is to get you 2 to 12 quotes.
We put the quotes next to each other and explain where the cover and the price differ. Tell us which one you want and we'll set it up with that insurer.
Expect to hear from your broker at least 30 days before the policy runs out. If you need to claim, for example after a break-in or a fire, call your broker and they'll put your case to the insurer.
Get a quotePub insurance questions
Rather talk it through with someone? Ring a broker on 1800 556 777.
You'll only know the figure once insurers have quoted on your venue, and every state adds a tax to the price. They look at the type of venue, its location, whether the building is yours and what you've claimed in the past. Comparing several quotes shows you how far apart the prices are.
Workers compensation if the pub employs staff, and CTP insurance, for people injured by a vehicle the pub runs. The workers compensation rules, including any exemption, differ by state and territory. Some states and territories also make public liability compulsory for certain occupations. Beyond that, business.gov.au says "other types of insurance are your choice".
Not across the board: business.gov.au says only certain occupations need it by law, and only in some states and territories. It pays when someone gets hurt, or something of theirs is damaged, through your negligence, meaning you didn't take reasonable care.
You might, because business.gov.au says a business that makes, sells or supplies goods may need it, and every meal and drink a pub serves counts. It deals with a guest's claim that something your pub supplied injured them or damaged their belongings.
Yes, wherever the venue is in Australia. We're based at Grace Insurance's head office in Joondalup, and Grace has five more offices, from Darwin down to Melbourne.
No, we're brokers. We put your venue in front of insurers, help you weigh up their quotes and set up the policy you pick. That insurer is the one that issues it.
We aim to have a broker in touch within 24 hours of your form coming through. If you'd rather talk now, the office takes calls on weekdays between 8:30am and 5pm, Perth time.
Yes, it's part of Grace Insurance, the Australian-owned brokerage Frans du Plessis has run out of Perth since 2015. Frans's broking career goes back to 1992.
Whether your policy is up for renewal or you've just taken over the venue, a broker can get insurers quoting on your cover.