
Covers
Building, contents and stock insurance for pubs
Building, contents and stock insurance is for the pub itself: the building, the bar and fixtures you own, and the beer, wine and food not yet sold.
01
What you can insure
We can arrange commercial property cover, as brokers call it, for each of these.
 12345
- 1
The building
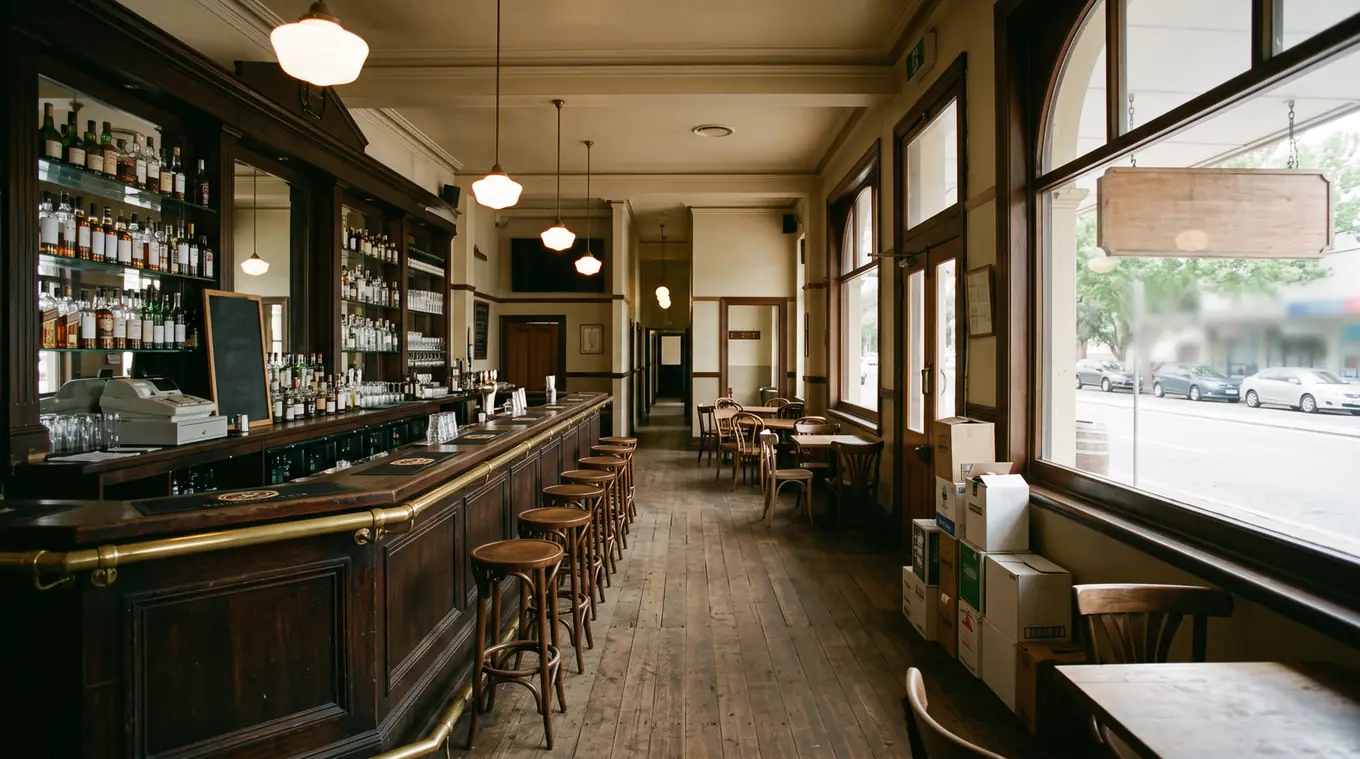
Walls, roof, floors and the rest of the structure, if the freehold is yours, meaning you own the building and the land.
- 2
The fit-out
The bar counter, back bar, cool room walls and other work a shopfitter put in.
- 3
Furniture and fixtures
Stools, tables, beer garden benches, lights and anything fixed in place.
- 4
Signage
The sign over the door and the boards out the front.
- 5
Stock
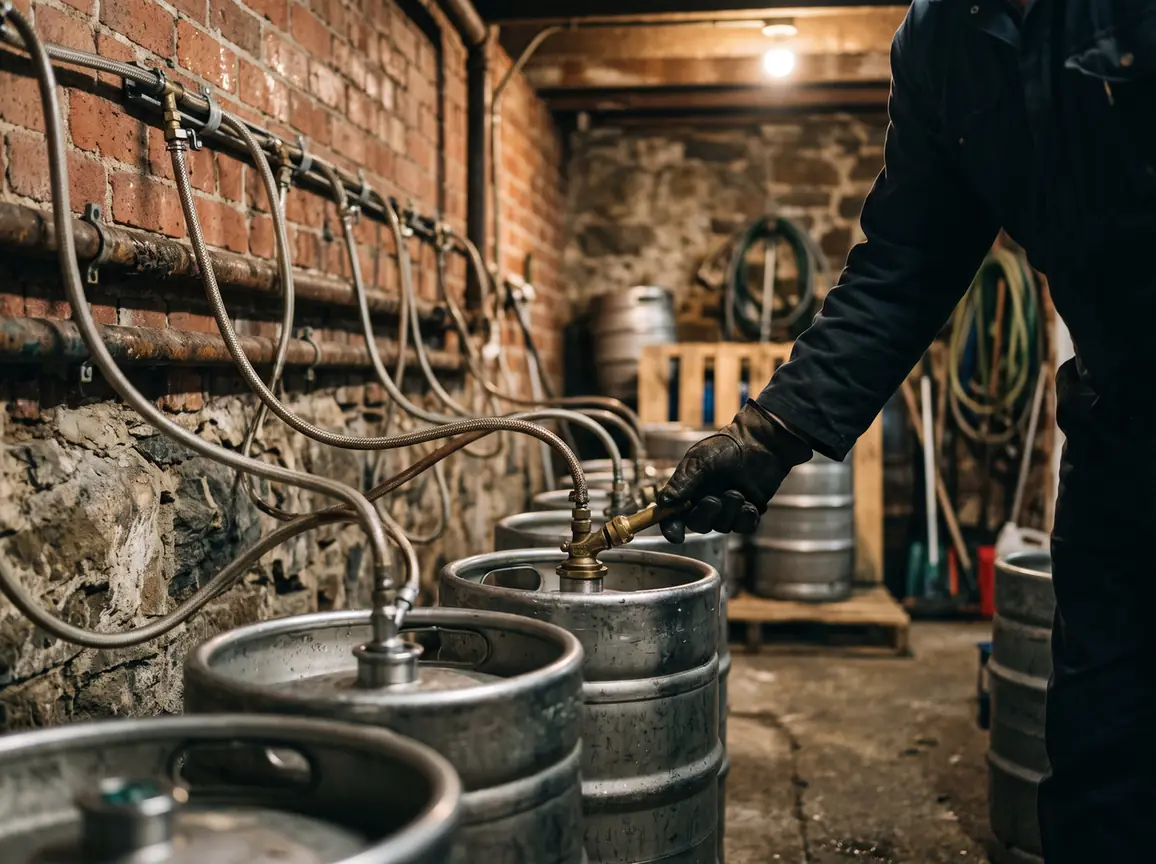
The beer in the kegs, plus cartons, spirits, wine and the food in the kitchen.
02
Storms, fires, theft and accidents
Grace Insurance, the company our brokers work for, gives these as examples of what property cover can pay out for. Your own policy's written terms, known as the policy wording, say which of them are covered and when.
Fire
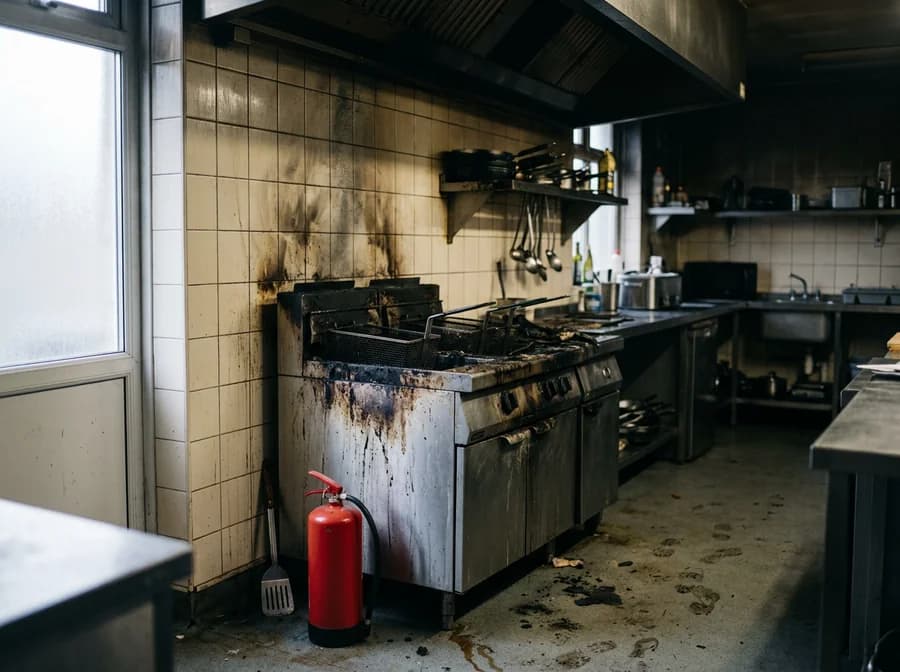
A fryer fire in the kitchen, or a fire that starts from faulty wiring in the cellar.
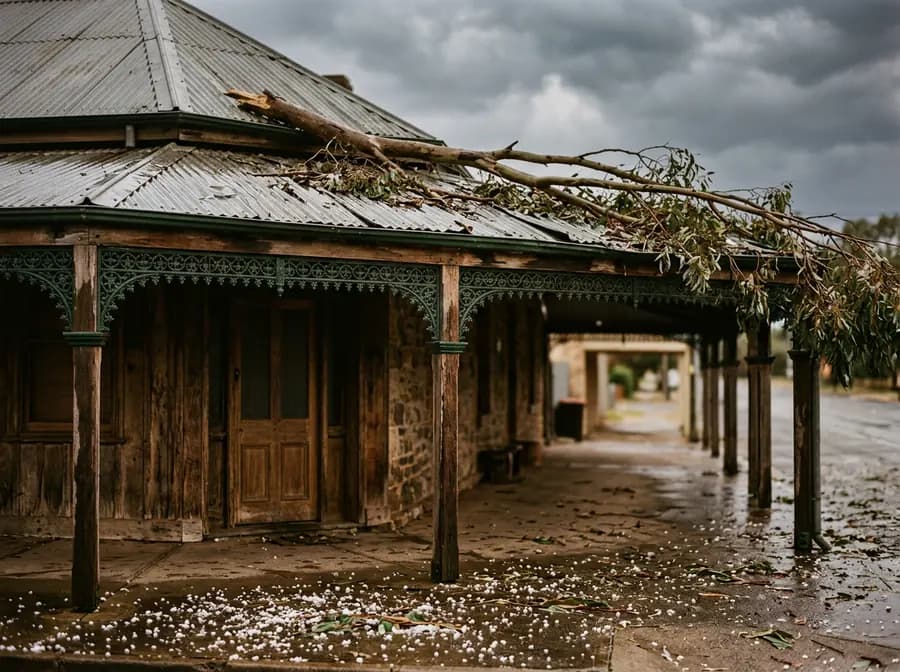
Storm
Hail through the skylights or a gum tree branch on the roof.
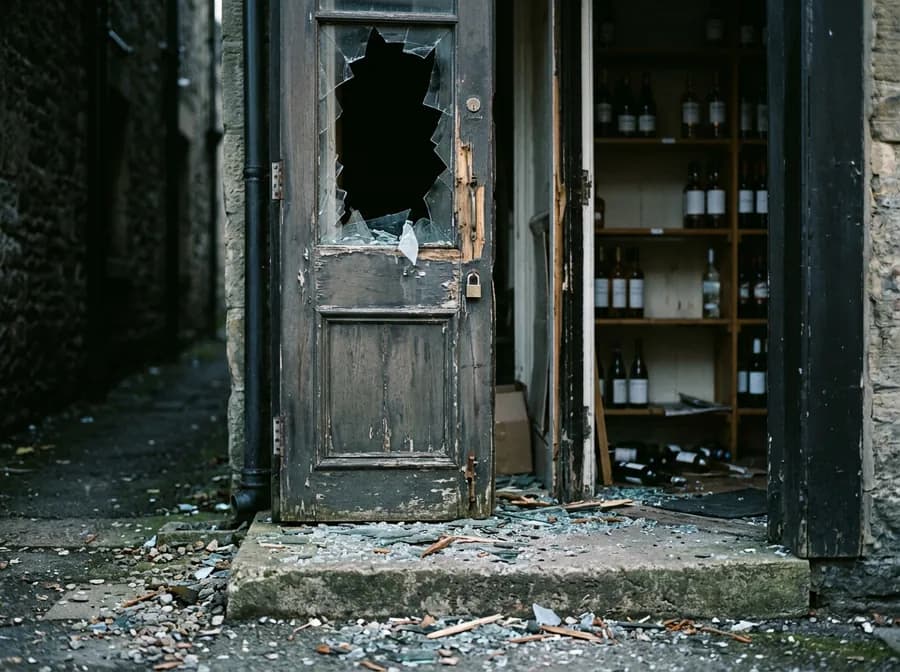
Theft
Thieves force the back door after closing and take the TVs off the walls.
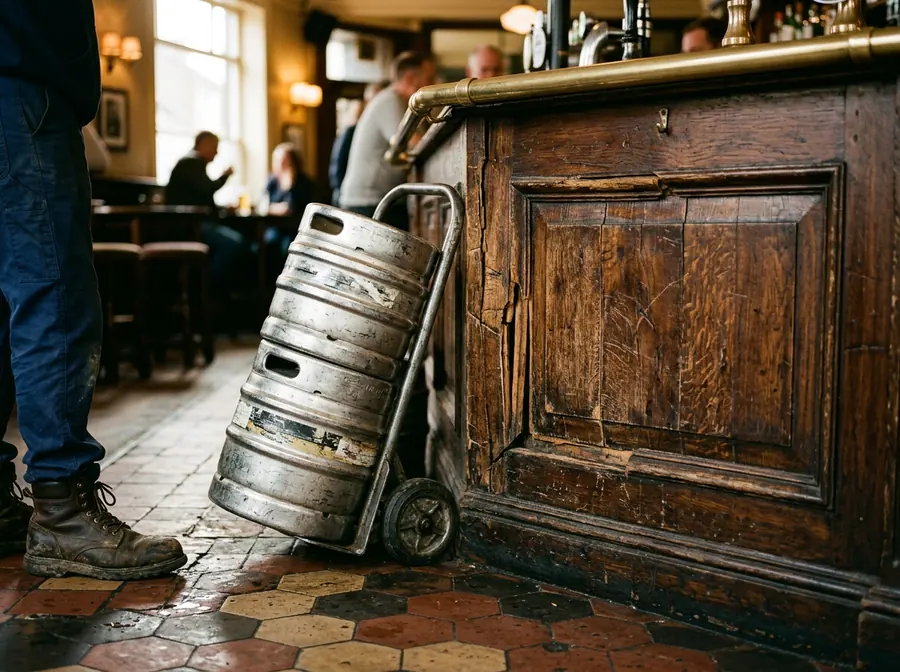
Accidental damage
A delivery trolley that cracks the bar front.
03
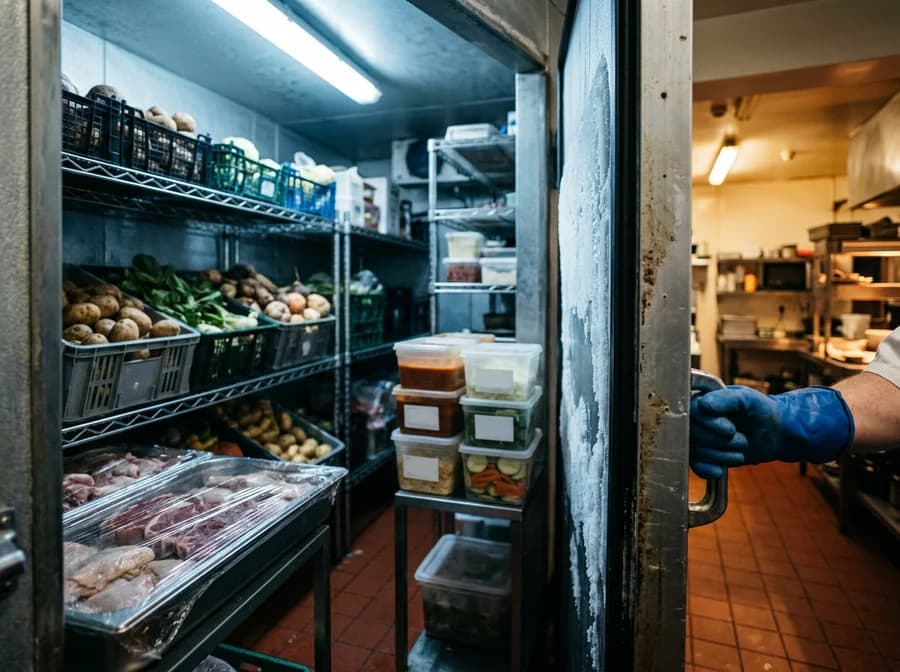
Food that goes off in a breakdown
If a freezer or the cool room breaks down and food goes bad, there's a cover for that loss, which business.gov.au calls deterioration of stock. If your bistro keeps plenty of meat and seafood on hand, get it quoted at the same time.
04
Getting the figures right
Before you ask for quotes, put a price on refitting the bar, restocking the cellar and kitchen and, for freehold owners, rebuilding the pub. The Insurance Council of Australia lists guessing among the most common causes of underinsurance, where the payout doesn't cover the whole bill. Its advice is to use a calculator.
05
Property by venue
Each type of venue keeps different things of value on site, so the figures your broker asks for change too.
Give your broker separate figures for the brewing equipment or still, and for the finished kegs, cans and bottles.
Value the wine in tanks and barrels, not only the cases on the shelves. Ask whether each insurer counts unfinished wine as stock.
Include the speakers, lighting rig and dance floor in your contents figure, along with the drinks in the cool room.
If the club owns its grounds, count the grandstand, sheds, fences and scoreboard as well as the clubhouse.
Property cover questions from publicans
Who insures the building comes down to what you and the landlord agreed, so keep the lease nearby when you call us. Either way, you can still insure the beer and food, the tables and chairs, and the bar if it's yours rather than the landlord's.
No. A patron's injury claim goes to public liability. Property cover is about the building, bar and stock you own.
Base it on what rebuilding the pub would cost today, and update the figure each year or after you renovate. Insurers can pay less on a claim when the building is insured below its value.
Use the most stock you carry at any time of year, and let us know when that is. A figure from a quiet month could leave you short if you claim at your busiest time.