
Covers
Business interruption insurance for pubs
Business interruption insurance supports a pub when an insured event, meaning something your policy covers, stops it trading. It can make up lost takings and pay some of the running costs while you're shut.
01
The two things it can help with
One policy can help with both of these, and our brokers arrange it for licensed venues in every state and territory.
Lost income
The trade you miss out on while the doors stay shut.
Ongoing costs
Some of the running costs that carry on while you're closed.
02
How a claim comes about
- 1
An insured event
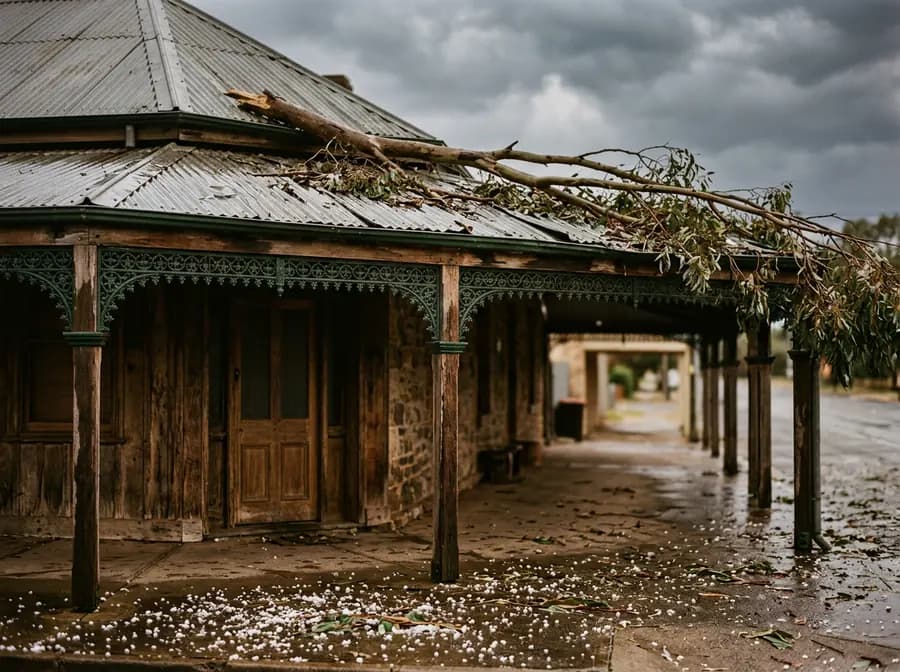
A storm takes part of the roof off, or a fire guts the kitchen.
- 2
The venue can't trade
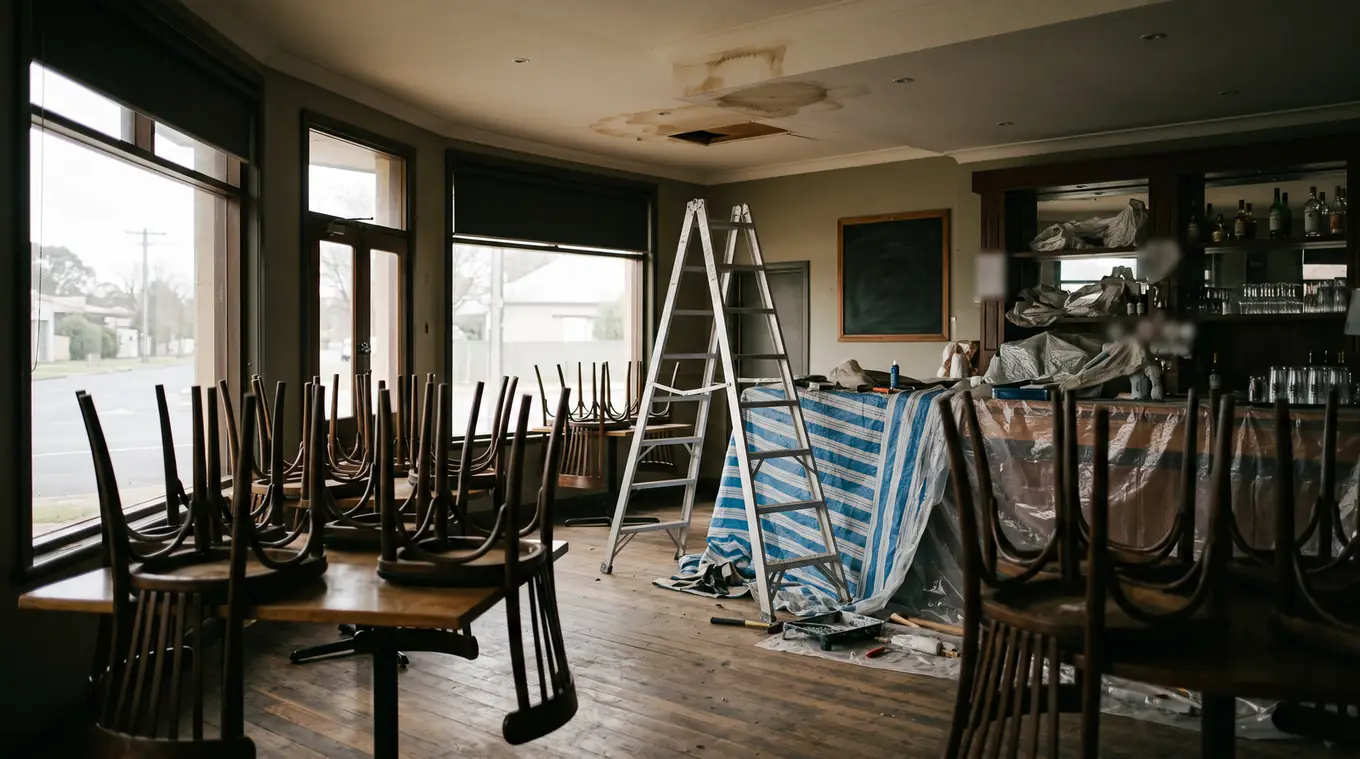
The pub can't open, or can't use the bar or kitchen, until the repairs are done.
- 3
The claim
You claim for lost takings and the costs your policy covers.
Both business.gov.au and Grace Insurance, which we're part of, describe this cover as paying out after an insured event. If the pub shuts for some other reason, ask your broker what the policy says.
03
When equipment breaks down
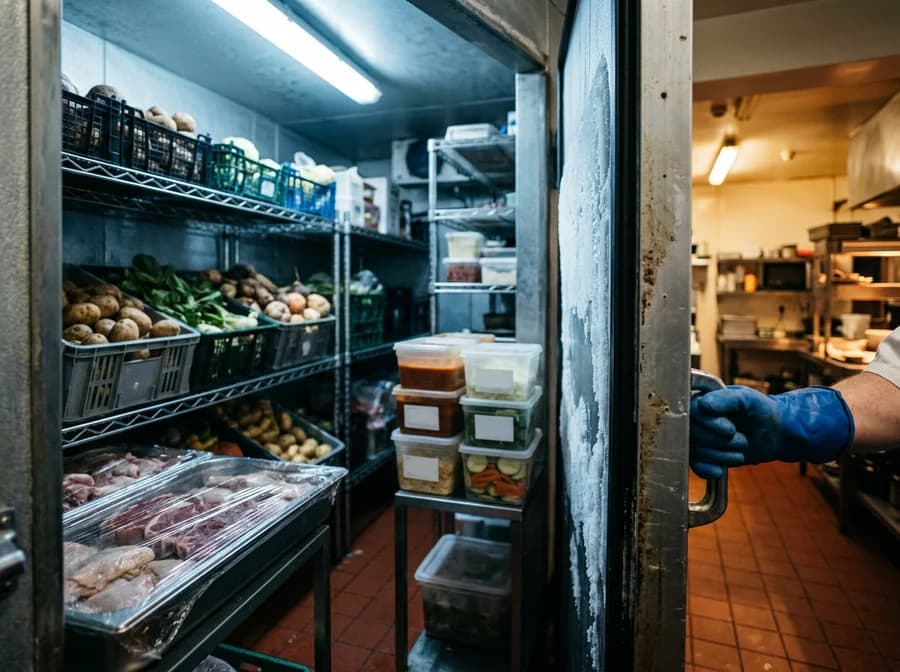
When the compressor that does the cooling in your cool room dies, the repair bill goes to machinery breakdown cover. Ask your broker whether any of your quotes would pay for lost trade while the cool room is out of action.
04
Questions to take to your broker
How long will it pay for?
Ask how many weeks or months each insurer would pay, and whether the pub could be rebuilt and trading again by then.
Which costs are included?
Bring a list of your regular bills, like rent, payroll and the bank loan, and ask which ones each quote would cover.
What figures do insurers want?
Ask your broker which numbers from your books the insurers want to see, so you can have them ready.
05
Closures by venue
What a closure costs you depends on when and how the venue makes its money.
Say which nights you open and roughly what each one takes.
A fire in the brewhouse can leave the taproom with nothing to pour. Your broker will ask what share of income comes from the taproom and what share from selling to bottle shops and other venues.
Point out your busiest months for cellar door visitors, since a closure then would cost the most.
If the club hosts weddings and functions, say how far ahead they're booked, as a closure could mean cancelling them.
What publicans ask about this cover
Building and contents cover handles the repairs and replacements. Lost takings while you're shut come under business interruption, and one quote request can cover both.
That's up to your current insurer, and your broker can ask them. The form asks which insurer you're with, so your broker knows who to ring.
The examples business.gov.au and Grace give involve damage to the venue, like a kitchen fire or storm damage. A blackout that starts somewhere else isn't one of them, so ask your broker to check what each quote says about it.
business.gov.au doesn't list it among the insurances a business can be required to hold by law, so it's up to you. If you'd like to see the price, add it to your quote request.