
Covers
Public liability for pubs and bars
Public liability insures your venue against claims by people outside the business, such as customers, suppliers and the neighbours. It comes into play when someone says they were injured, or something they own was damaged, because the venue was careless.
01
Injury, distress, damage and lost trade
business.gov.au sets out four types of claim, and in every one your negligence has to be the cause. Negligence means carelessness, such as leaving a hazard that a careful publican would have spotted and fixed.
1
Injury or death
A patron gets injured or dies, and the venue is to blame.
2
Damaged property
A neighbour's fence or a supplier's van is damaged.
3
Distress and psychiatric illness
Emotional distress, or a mental illness a doctor has diagnosed.
4
Consequential loss
Trade another business loses through your negligence. Say a fire in your kitchen spreads next door, and that business can't trade for weeks.
02
Where claims start in a licensed venue
 1234
- 1
The floor by the bar
Wet tiles where drinks get spilt and the mop has just been through.
- 2
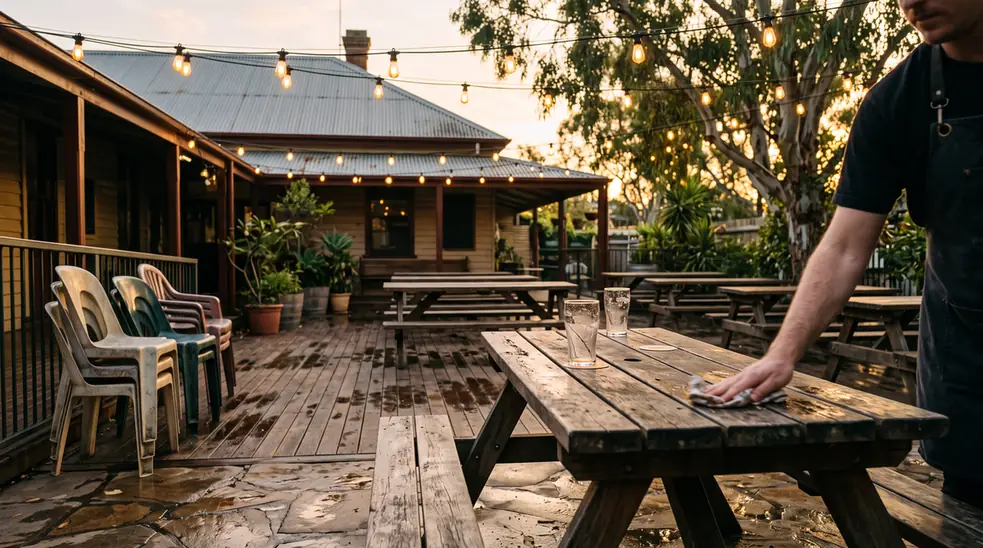
The deck
A loose or split board someone catches a heel on.
- 3
The courtyard
A stack of chairs that falls on someone.
- 4
A patron's things
A handbag your staff spilt a tray of drinks over.
Whether a claim like that gets paid depends on how it happened and on your policy.
03
Serving alcohol
A licensed venue's public liability can take in claims tied to serving alcohol. Before you settle on a quote, ask your broker to point out what it says about those claims.
04
Public liability or products liability
Public liability
Claims that the venue's carelessness hurt someone. business.gov.au's examples include food that makes a customer sick.
Products liability
Can cover goods you sell, from the bar, kitchen or bottle shop, that cause an injury, a death or damaged property.
If a diner fell ill after a meal in your bistro, ask your broker how each quote would deal with that claim.
05
The limit on a claim
Your limit sets a dollar ceiling, and the insurer won't pay above it on a claim. Before you choose a policy, your broker goes over the limit on each quote with you.
Getting it priced
We're brokers, which means we go to insurance companies for you rather than selling policies of our own. Over 160 insurers are on our list, and your broker will try to get you between 2 and 12 quotes.
We aim to reply within 24 hours, whether you call or use the form.
07
Public liability by venue
The questions insurers ask about public liability change with the kind of venue.
Say how many people your licence allows in, when you close, and whether a security firm supplies your door staff.
Sporting clubs should mention any games, bowls greens or events that bring in visitors.
If visitors walk through the brewery or see the still, describe how close they get to hot or pressurised equipment.
Say whether guests only taste or can also buy wine by the glass, and list any weddings, concerts or other events you host.
Public liability and your venue's other covers
No, that's what building, contents and stock cover is for. Public liability looks after claims from other people.
Yes. The form lets you pick public liability by itself, or add any other covers you'd like priced.
Staff injuries go to workers compensation, which most employers are required by law to hold. Public liability covers everyone else, like customers and suppliers.
It might, if you apply for outdoor dining or run an event. Each council sets its own amount, and several we checked want $20 million. Ask yours before you get quotes.